Why Global Investors Are Watching Korea's Primary K-IFRS Filings (SeAH Steel Holdings, TYM Corp, LG HelloVision) Under a 4.90% US 10Y Yield Regime
Cross-checking DART primary financial statements against USD/KRW (1,340.7), PHLX Semiconductor (10,300.95), and Asia's industrial policy vectors.
Act I — The Macro, FX & Policy Backdrop
Global equity markets are navigating a high-dispersion regime: with the KOSPI at 5,683.80, the PHLX Semiconductor Index (SOX) at 10,300.95, USD/KRW at 1,340.73, and the U.S. 10-Year Treasury Yield at 4.90%, top-down index beta masks violent rotation underneath the surface.
- Cross-Market Sector Dispersion: KRX resilience (KOSPI +0.62%) despite US semiconductor volatility (SOX -11.84%) highlights rotation toward upstream Korean suppliers printing hard 3Q26 operating profit
- FX Translation Vector: Constructive USD/KRW (1,340.7) equilibrium supporting K-IFRS export operating margins while stabilizing foreign institutional FX flows
- Discount-Rate Discipline: Higher-for-longer US 10Y yield (4.90%) penalizing long-duration narratives and rewarding verified K-IFRS operating cash flow & sub-1.0x P/B balance sheets
- Korea Corporate Value-Up Mandate, Commercial Act Reform & Treasury Share Rules: Regulatory pressure from the KRX Value-Up Program, proposed Commercial Act fiduciary-duty amendments, and FSC restrictions on treasury-share arbitrage are forcing a structural bifurcation: sub-0.8x P/B companies with positive operating cash flow face mounting activist and policy catalysts to cancel shares and raise payouts.
- Fed–BOK Monetary Policy Divergence & US Trade/Tariff (IEEPA) Transmission: With the Federal Reserve maintaining real-rate discipline and the Bank of Korea constrained by FX stability and domestic debt ratios, equity dispersion favors a barbell between dollar-invoicing AI/grid exporters and deeply discounted KRX balance-sheet compounders.
Act II — Primary K-IFRS Filing Evidence (FSS OpenDART)
1. SeAH Steel Holdings (KRX: 003030) — UNDERVALUED
In its latest primary DART filing (연결재무제표기준영업(잠정)실적(공정공시), Receipt No. 20261104800342),
SeAH Steel Holdings reported revenue of 921.0B KRW (~$686.9M USD) and operating profit of
38.7B KRW (+99.6% YoY), translating into a verified K-IFRS operating margin of 4.20%.
Valuation & Multiples Snapshot: Market Cap: 879.4B KRW | P/Ann.OP: 5.7x | P/B: 0.40x | P/E: 5.80x | Global Peer Benchmark: $NUE $STLD
Macro & Policy Read-Through: Reported preliminary operating profit of 38.7B KRW (QoQ -2.5%, YoY +99.6% (4.20% OPM)), placing the 879B KRW market cap at 5.7x annualized OP and 0.40x P/B. Key catalyst is confirming non-operating FX/finance spreads in the full quarterly footnotes. Against a 1,340.7 USD/KRW exchange rate and a 4.90% US 10-year Treasury yield, investors are pricing the spread between realized operating cash flow and tangible book value.
2. TYM Corp (KRX: 002900) — UNDERVALUED
In its latest primary DART filing (연결재무제표기준영업(잠정)실적(공정공시), Receipt No. 20261104800289),
TYM Corp reported revenue of 229.0B KRW (~$170.8M USD) and operating profit of
16.3B KRW (+771.7% YoY), translating into a verified K-IFRS operating margin of 7.10%.
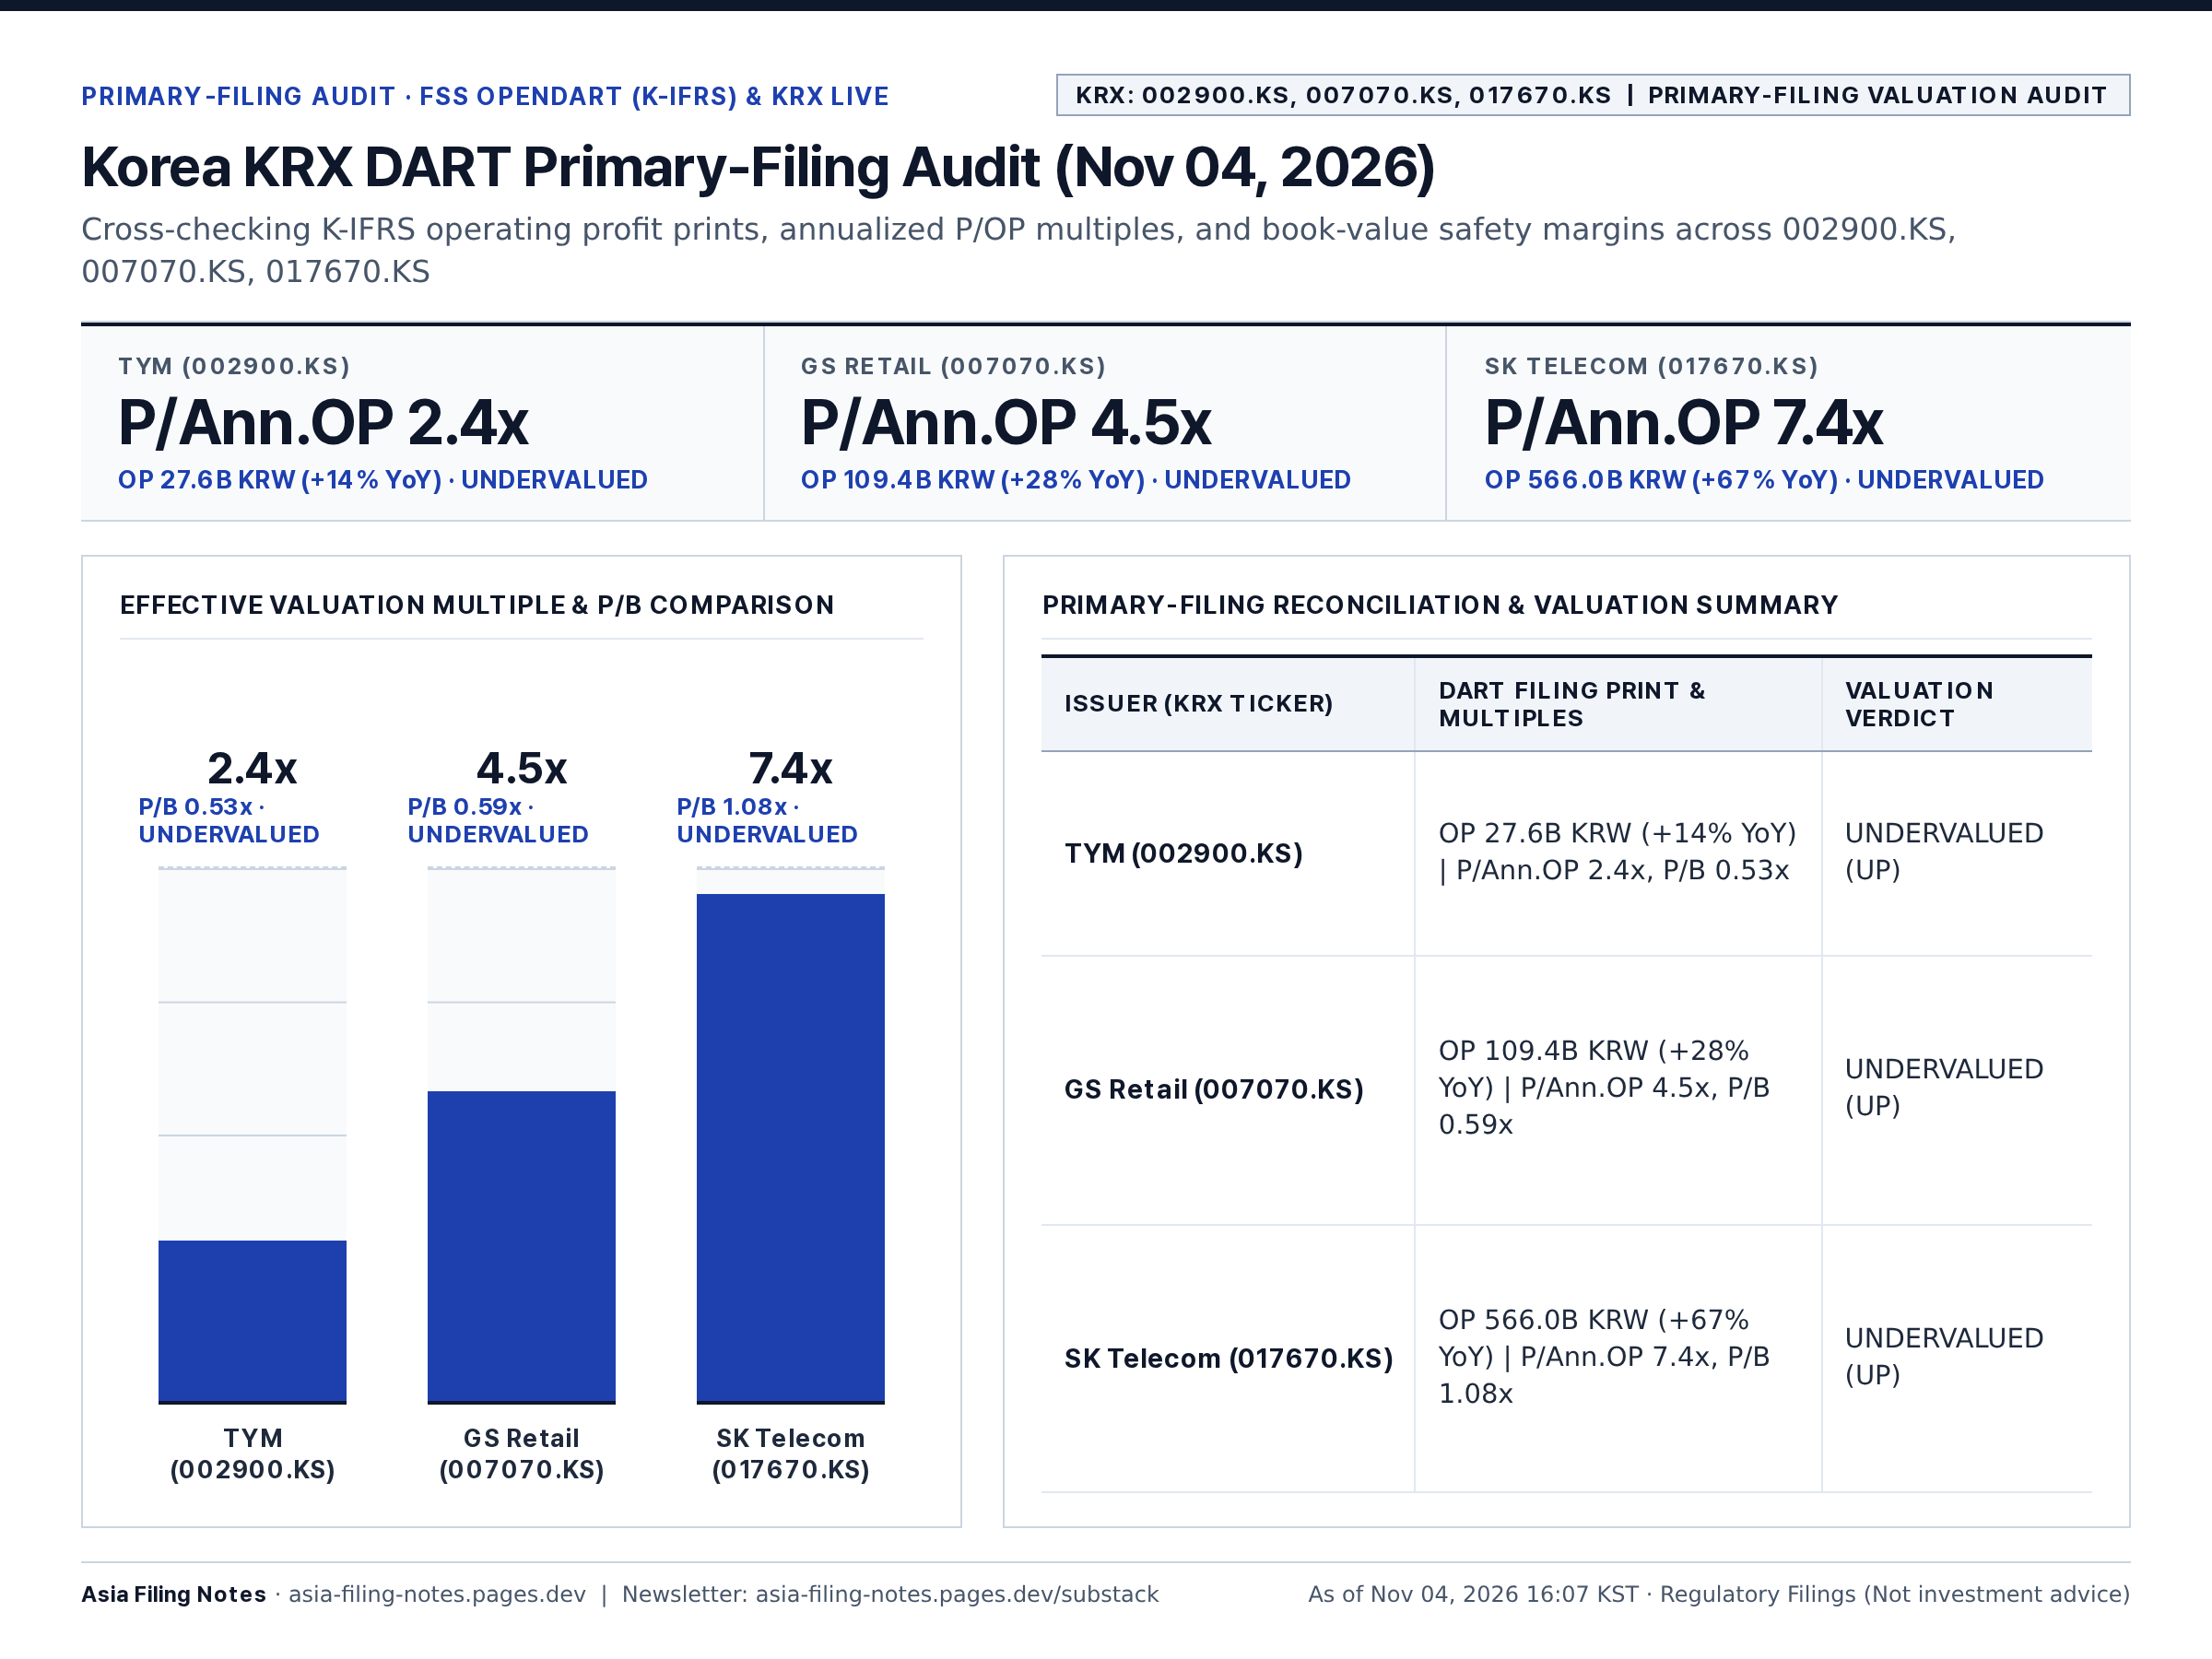
Valuation & Multiples Snapshot: Market Cap: 247.2B KRW | P/Ann.OP: 3.8x | P/B: 0.56x | P/E: 10.60x | Global Peer Benchmark: $DE $CAT
Macro & Policy Read-Through: Reported preliminary operating profit of 16.3B KRW (QoQ -30.1%, YoY +771.7% (7.10% OPM)), placing the 247B KRW market cap at 3.8x annualized OP and 0.56x P/B. Key catalyst is confirming non-operating FX/finance spreads in the full quarterly footnotes. Against a 1,340.7 USD/KRW exchange rate and a 4.90% US 10-year Treasury yield, investors are pricing the spread between realized operating cash flow and tangible book value.
3. LG HelloVision (KRX: 037560) — UNDERVALUED
In its latest primary DART filing (연결재무제표기준영업(잠정)실적(공정공시), Receipt No. 20261104800215),
LG HelloVision reported revenue of 291.0B KRW (~$217.0M USD) and operating profit of
9.0B KRW (+172.8% YoY), translating into a verified K-IFRS operating margin of 3.10%.
Valuation & Multiples Snapshot: Market Cap: 219.9B KRW | P/Ann.OP: 6.1x | P/B: 0.43x | P/E: 12.10x | Global Peer Benchmark: $CMCSA $CHTR
Macro & Policy Read-Through: Reported preliminary operating profit of 9.0B KRW (QoQ -14.3%, YoY +172.8% (3.10% OPM)), placing the 220B KRW market cap at 6.1x annualized OP and 0.43x P/B. Key catalyst is confirming non-operating FX/finance spreads in the full quarterly footnotes. Against a 1,340.7 USD/KRW exchange rate and a 4.90% US 10-year Treasury yield, investors are pricing the spread between realized operating cash flow and tangible book value.
Act III — Cross-Market Takeaway & Primary Filing Portal
When evaluating Asian semiconductor, grid hardware, and deep-value industrial names alongside U.S. benchmarks, primary K-IFRS footnote discipline separates structural margin expansion from one-off FX or accounting noise.
Originally published at https://asia-filing-notes.pages.dev/posts/en-krx-20261104_1607-live-dart-audit/ (Asia Filing Notes). Personal analysis record based on public regulatory filings and market data. Not investment advice or a solicitation to buy or sell any security.