Korea AI Second-Derivative Audit (Oct 29–30 DART): KOSPI Transformers & Substrates vs. KOSDAQ Fab Specialists
| Issuer & Live Multiples | Valuation Estimate | 6–12M Direction | So What? (Valuation Basis & Catalyst) |
|---|---|---|---|
| Daeduck Elec (353200.KS) Mkt Cap 5.84T KRW · Fwd P/E 26.1x · Cap/Ann.OP 16.6x | UNDERVALUED | ▲ Bullish | OPM jump (8.5% -> 21.0%) rapidly compresses forward earnings multiple |
| TCK (064760.KQ) Mkt Cap 2.15T KRW · Fwd P/E 20.2x · Cap/Ann.OP 17.8x | UNDERVALUED | ▲ Bullish | 27.5% OPM consumable monopoly trading at an attractive 20.2x Fwd P/E |
| Raon Robotics (232680.KQ) Mkt Cap 176B KRW · P/E 37.5x · Cap/Ann.OP 11.2x | UNDERVALUED | ▲ Bullish | 3Q OP breakout (14.8% OPM) brings annualized OP multiple down to 11.2x |
| Hyosung Heavy (298040.KS) Mkt Cap 19.04T KRW · Fwd P/E 25.3x · Cap/Ann.OP 19.5x | FAIR VALUE | ▲ Constructive | +43.3% YoY pre-tax profit growth justifies 25.3x forward multiple |
| Samsung Electro (009150.KS) Mkt Cap 89.78T KRW · P/E 92.6x · Fwd P/E 54.3x | OVERVALUED | ▶ Selective | 879B KRW MLCC contract is solid, but Fwd P/E 54.3x prices in steep recovery |
Beyond Samsung & SK Hynix: Oct 29–30 DART filings show OP surging +259.4% YoY at KOSPI substrate maker Daeduck Electronics and +596.1% QoQ at KOSDAQ wafer-robot maker Raon Robotics.
As of 2026.10.31 · Source: Korean FSS DART K-IFRS Preliminary 3Q26 Earnings & Single-Sales Contracts (2026.10.29–10.30) · Derived ratios marked (Calc.).
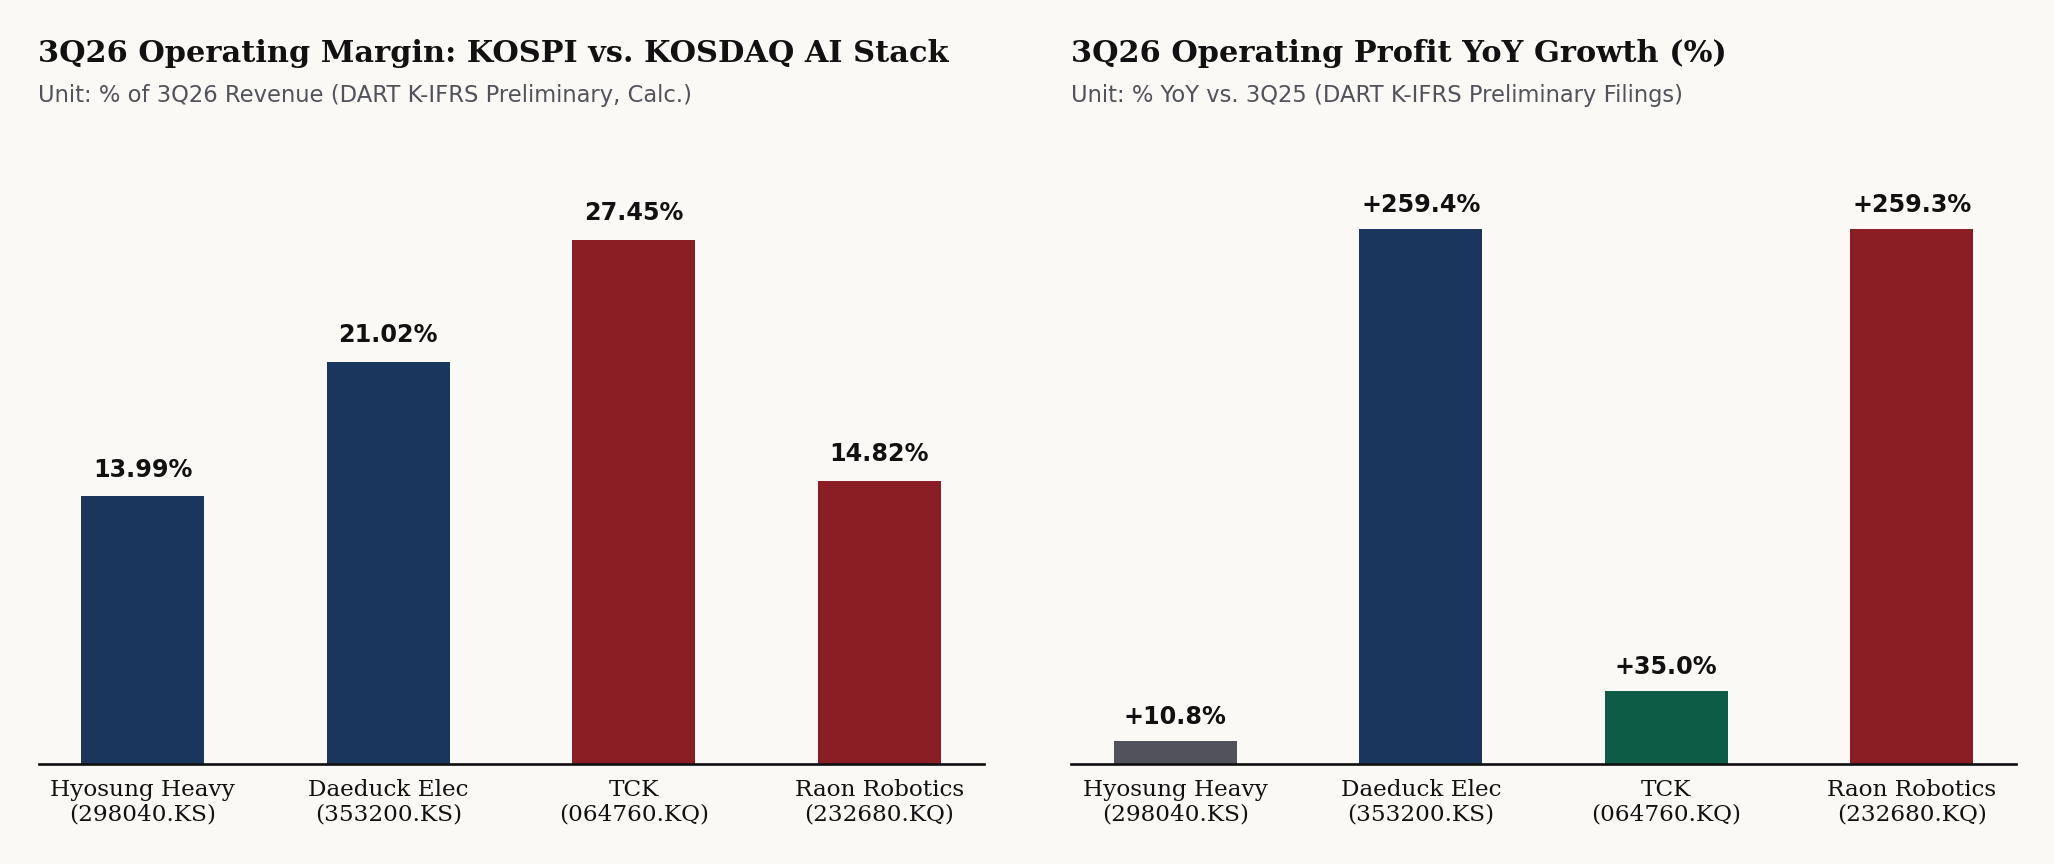
Left: 3Q26 operating margin comparison across KOSPI (Hyosung Heavy 298040.KS, Daeduck Electronics 353200.KS) and KOSDAQ (TCK 064760.KQ, Raon Robotics 232680.KQ). Right: 3Q26 YoY operating profit growth from official DART preliminary filings [1][2][4][5].
1. KOSPI AI Infrastructure Spine: Grid Transformers (`298040`), Substrates (`353200`) & MLCC (`009150`)
- Market Structure: KOSPI houses heavy grid transformers, MLCCs, and FC-BGA substrates; KOSDAQ houses SiC etch consumables, vacuum wafer robotics, and cleanroom equipment inside Korean fabs [1][2][3][4][5][6][7].
- Hyosung Heavy Industries (`298040.KS`): 3Q26 revenue 1,740,635M KRW (+7.17% YoY, +3.18% QoQ); OP 243,455M KRW (-7.88% QoQ; 13.99% OPM Calc. vs. 15.67% in 2Q26; 9M26 OP 660,064M KRW, +35.69% YoY). Pre-tax continuing income jumped +18.31% QoQ (+43.25% YoY) to 280,237M KRW; Net profit 226,303M KRW (+31.77% QoQ, +49.11% YoY) [1].
- Daeduck Electronics (`353200.KS`): 3Q26 revenue 418,115M KRW (+46.1% YoY, +4.3% QoQ); OP surged +259.4% YoY (+25.0% QoQ) from 24,448M to 87,871M KRW → OPM expanded +12.48pp YoY from 8.54% to 21.02% (Calc.); 9M26 OP up +941.4% YoY (209,446M vs. 20,112M KRW) [2].
- Samsung Electro-Mechanics (`009150.KS`): Filed a 1-year MLCC supply contract for 879,285.4M KRW (US$658.0M @ 1,336.30 KRW/USD) = 7.8% of FY25 revenue (11,314,459.2M KRW) [3]. Standard KRX contract terms: zero upfront deposit (
계약금ㆍ선급금 유무: 무) and counterparty identity withheld under trade-secret protection until Dec 21, 2027 [3].
| Issuer (Market & Ticker) | Verified Oct 29–30 DART Filing Figures (3Q26 / Contract) |
|---|---|
| Hyosung Heavy Industries (KOSPI: 298040.KS) |
3Q26 Rev 1,740,635M KRW (+3.18% QoQ, +7.17% YoY; 9M26 4,785,822M KRW, +13.26% YoY); OP 243,455M KRW (-7.88% QoQ, +10.76% YoY; 9M26 660,064M KRW, +35.69% YoY) → 13.99% 3Q26 OPM (Calc.); Pre-tax income 280,237M KRW (+18.31% QoQ, +43.25% YoY); Net profit 226,303M KRW (+31.77% QoQ, +49.11% YoY) [1] |
| Daeduck Electronics (KOSPI: 353200.KS) |
3Q26 Rev 418,115M KRW (+4.3% QoQ, +46.1% YoY; 9M26 1,165,404M KRW, +55.9% YoY); OP 87,871M KRW (+25.0% QoQ, +259.4% YoY; 9M26 209,446M KRW, +941.4% YoY) → 21.02% 3Q26 OPM (Calc. vs. 8.54% in 3Q25); Net profit 54,376M KRW (+133.6% YoY) [2] |
| Samsung Electro-Mechanics (KOSPI: 009150.KS) |
MLCC supply contract for 879,285.4M KRW (US$658.0M at 1,336.30 KRW/USD) = 7.8% of FY25 consolidated revenue (11,314,459.2M KRW); period 2026.12.21–2027.12.21; zero advance payment; counterparty withheld until 2027.12.21 [3] |
| TCK (Tokai Carbon Korea) (KOSDAQ: 064760.KQ) |
3Q26 standalone Rev 110,102M KRW (+16.05% QoQ, +38.95% YoY; 9M26 300,366M KRW, +30.44% YoY); OP 30,219M KRW (+12.55% QoQ, +35.04% YoY; 9M26 85,622M KRW, +31.02% YoY) → 27.45% 3Q26 OPM (Calc.; 9M26 OPM 28.51% Calc.) [4] |
| Raon Robotics (KOSDAQ: 232680.KQ) |
3Q26 standalone Rev 26,535M KRW (+45.9% QoQ, +104.7% YoY; 9M26 58,863M KRW, +51.3% YoY); OP 3,933M KRW (+596.1% QoQ vs. 565M KRW, +259.3% YoY vs. 1,095M KRW) → 14.82% 3Q26 OPM (Calc. vs. 3.11% in 2Q26) [5] |
| Wort & Withtech (KOSDAQ: 396470.KQ / 348350.KQ) |
Wort: 1,638.0M KRW THC contract with Samsung Electronics (10.76% of FY25 rev 15,220.9M KRW; Hwaseong/Pyeongtaek fabs through 2027.05.31) [6]. Withtech: 13,044.0M KRW TMS O&M contract with Samsung Electronics (22.56% of FY25 rev 57,807.0M KRW; 2026.11.01–2027.12.31) [7] |
2. KOSDAQ Fab-Floor Specialists: Etch Rings (`064760`), Wafer Robots (`232680`) & Pyeongtaek Orders (`396470`, `348350`)
- TCK (`064760.KQ` — SiC Etch Consumables): 3Q26 revenue 110,102M KRW (+16.05% QoQ, +38.95% YoY); OP 30,219M KRW (+12.55% QoQ, +35.04% YoY) → 27.45% OPM (Calc.); 9M26 OPM 28.51% (Calc.) on 300,366M KRW revenue [4].
- Raon Robotics (`232680.KQ` — Vacuum Wafer Robots): 3Q26 standalone revenue 26,535M KRW (+45.9% QoQ, +104.7% YoY); OP surged +596.1% QoQ (+259.3% YoY) from 565M to 3,933M KRW → standalone OPM jumped from 3.11% (2Q26) to 14.82% (3Q26, Calc.) [5].
- Wort (`396470.KQ`) & Withtech (`348350.KQ`) — Direct Samsung Fab Contracts: Backing up Samsung's ~27.5T KRW implied 4Q26 facility investment balance (84.4T annual plan minus 56.9T 9M26), Wort signed a 1,638.0M KRW THC contract (10.76% of FY25 revenue of 15,220.9M KRW) for Samsung's Hwaseong/Pyeongtaek campuses through May 31, 2027 (100% cash within 30 days) [6], and Withtech signed a 13,044.0M KRW TMS maintenance contract (22.56% of FY25 revenue of 57,807.0M KRW) with Samsung Electronics through Dec 31, 2027 [7].
Takeaway & 4Q26 Falsification Trigger
- Core Hypothesis: 4Q26 revenue at KOSDAQ fab suppliers (TCK, Raon Robotics, Wort) will accelerate QoQ as Samsung executes its ~27.5T KRW 4Q facility investment balance and SK Hynix ramps M15X.
- Falsification Trigger: TCK or Raon Robotics 4Q26 revenue turns negative QoQ, or Wort's May 31, 2027 Hwaseong/Pyeongtaek delivery date is pushed out via a DART amendment (
기재정정) [4][5][6].
Sources
- DART Hyosung Heavy Industries (298040.KS) Preliminary Consolidated 3Q26 Earnings Fair Disclosure, 2026.10.30.
- DART Daeduck Electronics (353200.KS) Preliminary Consolidated 3Q26 Earnings Fair Disclosure, 2026.10.30.
- DART Samsung Electro-Mechanics (009150.KS) Single-Sales & Supply Contract Disclosure (MLCC), 2026.10.30.
- DART TCK (064760.KQ) Preliminary 3Q26 Earnings Fair Disclosure, 2026.10.29.
- DART Raon Robotics (232680.KQ) Preliminary 3Q26 Earnings Fair Disclosure, 2026.10.30.
- DART Wort (396470.KQ) Single-Sales & Supply Contract Disclosure (Samsung Electronics THC), 2026.10.30.
- DART Withtech (348350.KQ) Single-Sales & Supply Contract Disclosure (Samsung Electronics TMS), 2026.10.30.
Get Primary Korean DART (K-IFRS) & Asia Semiconductor Filing Notes Before Secondary Wires
Receive direct email alerts whenever a new Korean FSS DART preliminary earnings note, treasury-share burn check, or U.S. SEC CapEx cross-check is published. 100% free, one-way analytical record.
Reader Discussion & Filing Notes (0)
Discuss K-IFRS footnotes, DART
rcpNodisclosures, KOSPI/KOSDAQ valuation gaps, or test the falsifiable hypotheses in this note. Free reader accounts take 10 seconds to create.