KOSPI Auto Stack vs. KOSDAQ Tech (3Q26 DART): Why Headline Operating Profit Misses Pre-Tax Swings
| Issuer & Live Multiples | Valuation Estimate | 6–12M Direction | So What? (Valuation Basis & Catalyst) |
|---|---|---|---|
| Suprema (236200.KQ) Mkt Cap 362B KRW · P/E 7.07x · P/B 1.20x · Core OPM 17.3% | UNDERVALUED | ▲ Bullish | Core 17.3% OPM at 7.1x P/E is undervalued once non-operating FX/financial noise clears |
| Satrec Initiative (099320.KQ) Mkt Cap 632B KRW · Cap/Ann.3Q OP 19.2x · P/B 2.56x | UNDERVALUED | ▲ Bullish | 3Q OPM breakout to 14.7% compresses annualized operating multiple to 19.2x |
| SOOP (067160.KQ) Mkt Cap 373B KRW · P/E 4.36x · Fwd P/E 5.36x · P/B 0.77x | FAIR VALUE | ▶ Neutral | 4.4x P/E prices in YoY contraction; awaits top-line re-acceleration trigger |
| Hyundai Autoever (307950.KS) Mkt Cap 8.57T KRW · P/E 44.92x · Fwd P/E 40.44x · P/B 4.53x | OVERVALUED | ▼ Cautious | Fwd P/E 40.4x is stretched against 5.63% OPM and -23.9% QoQ OP contraction |
| HL Mando (204320.KS) Mkt Cap 1.64T KRW · P/E 9.68x · P/B 0.56x (3Q Net Loss) | OVERVALUED | ▼ Cautious | 2.22% OPM plus -92.7B KRW non-op loss creates a near-term earnings value trap |
Reading all 4 lines of the Korean DART preliminary table exposes a -92.74B KRW non-operating swing at KOSPI's HL Mando and a -23.52B KRW swing at KOSDAQ's Suprema—alongside a +502.7% QoQ OP breakout at Satrec Initiative.
As of 2026.10.31 · Source: Korean FSS DART K-IFRS Preliminary 3Q26 Earnings & Material Management Filings (2026.10.29–10.30) · Derived ratios marked (Calc.).
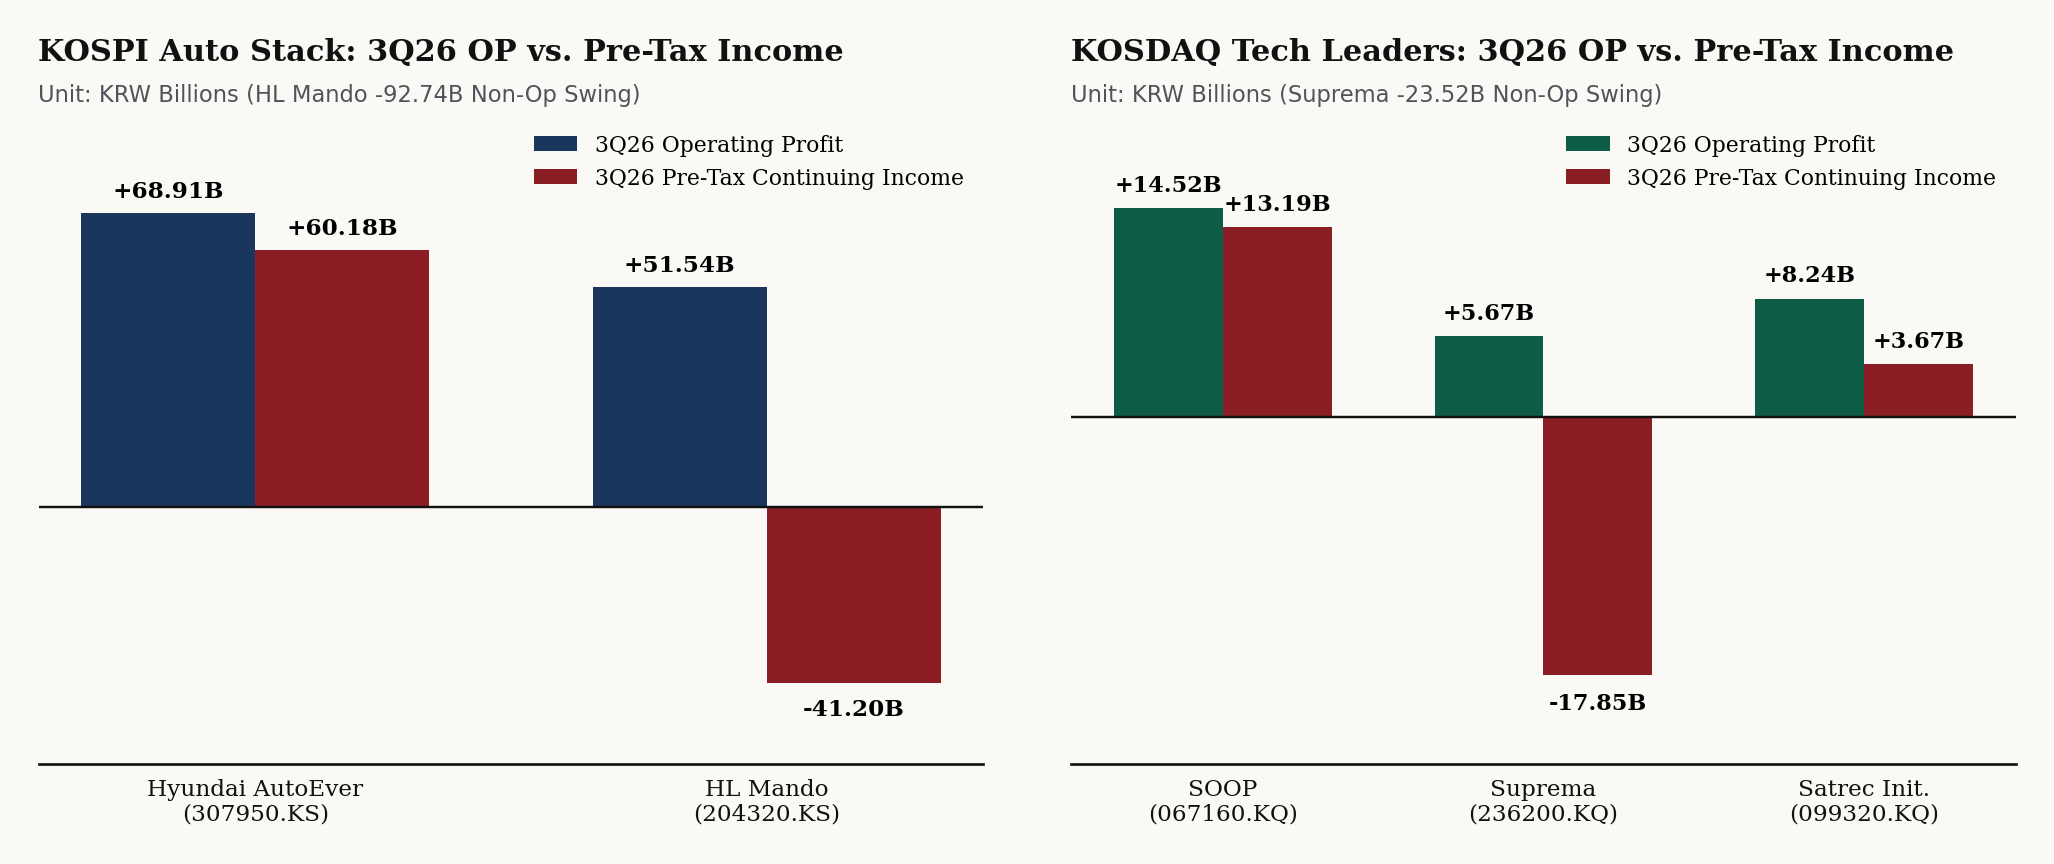
Left: 3Q26 Operating Profit vs. Pre-Tax Continuing Income at KOSPI's Hyundai AutoEver (307950.KS) and HL Mando (204320.KS, showing a -92.74B KRW non-operating swing). Right: 3Q26 Operating Profit vs. Pre-Tax Continuing Income across KOSDAQ's SOOP (067160.KQ), Suprema (236200.KQ, -23.52B KRW non-operating swing), and Satrec Initiative (099320.KQ) [2][3][4][5][6].
1. KOSPI Mobility Stack: Sequential OPM Compression & HL Mando's -92.74B KRW Non-Op Swing
- Why 4-Line DART Audits Matter: Korean preliminary filings (
연결재무제표기준 영업(잠정)실적 공정공시) print Revenue, OP, Pre-Tax Continuing Income, and Net Income [1][2][3][4][5][6][7]. Stopping at line 2 (OP) misses below-the-line FX/financial/impairment shocks. - Kia (`000270.KS`) & Hyundai AutoEver (`307950.KS`): Kia 3Q26 revenue 31,597,447M KRW (-4.4% QoQ, +10.1% YoY); OP 1,818,286M KRW (-30.8% QoQ, +24.3% YoY) → OPM compressed 7.96% (2Q26) → 5.75% (3Q26, Calc.); while OP rose +24.3% YoY, Pre-Tax fell -3.4% YoY (1,822,205M KRW) and Net Income fell -9.6% YoY (1,285,538M KRW) [1]. Hyundai AutoEver revenue 1,224,703M KRW (+16.2% YoY, -2.1% QoQ); OP 68,906M KRW (-23.9% QoQ, -2.6% YoY; 5.63% OPM Calc.); Pre-Tax 60,178M KRW (-34.3% QoQ, -14.7% YoY) [2].
- HL Mando (`204320.KS` — Positive OP, Pre-Tax Loss): 3Q26 revenue 2,320,530M KRW (0.0% YoY, -7.0% QoQ); OP +51,538M KRW (-51.8% QoQ, -45.3% YoY; 2.22% OPM Calc.) → Pre-Tax Continuing Income plunged to -41,197M KRW (vs. +92,695M KRW in 2Q26), a -92,735M KRW (-92.74B KRW) net non-operating deduction (Calc.), driving a controlling-interest net loss of -47,057M KRW [3]. Check Note 26/27 in the mid-November Q3 report.
| Issuer (Market & Ticker) | 3Q26 Operating Profit vs. Pre-Tax Continuing Income (DART) |
|---|---|
| Kia Corporation (KOSPI: 000270.KS) |
Rev 31.60T KRW (-4.4% QoQ, +10.1% YoY); OP 1.82T KRW (-30.8% QoQ, +24.3% YoY; 5.75% OPM Calc. vs. 7.96% in 2Q26); Pre-tax 1.82T KRW (-40.6% QoQ, -3.4% YoY); Net profit 1.29T KRW (-44.8% QoQ, -9.6% YoY) [1] |
| Hyundai AutoEver (KOSPI: 307950.KS) |
Rev 1,224.70B KRW (-2.1% QoQ, +16.2% YoY); OP 68.91B KRW (-23.9% QoQ, -2.6% YoY; 5.63% OPM Calc.); Pre-tax 60.18B KRW (-34.3% QoQ, -14.7% YoY); Net profit 44.93B KRW (-35.4% QoQ, -14.9% YoY) [2] |
| HL Mando (KOSPI: 204320.KS) |
Rev 2,320.53B KRW (-7.0% QoQ, 0.0% YoY); OP +51.54B KRW (-51.8% QoQ, -45.3% YoY; 2.22% OPM Calc.), but Pre-Tax Continuing Income swung to -41.20B KRW loss (-92.74B KRW non-op gap, Calc.); Net loss -42.51B KRW [3] |
| Suprema (KOSDAQ: 236200.KQ) |
Rev 32.84B KRW (-18.59% QoQ, +8.20% YoY); OP +5.67B KRW (17.26% OPM Calc.; 9M26 OPM 20.34% Calc.), but Pre-Tax Continuing Income swung to -17.85B KRW loss (-23.52B KRW non-op gap, Calc.); Net loss -12.64B KRW [4] |
| SOOP (KOSDAQ: 067160.KQ) |
Rev 105.69B KRW (+1.8% QoQ, -16.0% YoY); OP 14.52B KRW (+15.0% QoQ, -59.9% YoY; 13.74% OPM Calc. vs. 28.81% in 3Q25); Pre-tax 13.19B KRW (-19.3% QoQ, -65.1% YoY); Net profit 10.58B KRW (+21.0% QoQ, -64.0% YoY) [5] |
| Satrec Initiative (KOSDAQ: 099320.KQ) |
Rev 56.19B KRW (+9.9% QoQ, +11.4% YoY); OP 8.24B KRW (+502.7% QoQ vs. 1.37B KRW, +235.6% YoY; 14.66% OPM Calc. vs. 2.67% in 2Q26); Pre-tax 3.67B KRW (+698.5% QoQ); Net profit turned positive at 3.39B KRW [6] |
| AbClon (KOSDAQ: 174900.KQ) |
Final settlement & full IP assignment agreement with Yuhan Corporation on 2016 TIGIT antibody joint R&D contract; settlement receipt 1.00B KRW (≥10% of prior-year rev); zero remaining obligations or contingent liabilities [7] |
2. KOSDAQ Tech Divergence: Suprema (`236200`), SOOP (`067160`), Satrec (`099320`) & AbClon (`174900`)
- Suprema (`236200.KQ`): 3Q26 revenue 32,839M KRW (+8.20% YoY, -18.59% QoQ); OP 5,667M KRW (17.26% OPM Calc.; 9M26 OP 21,214M KRW, +7.24% YoY, 20.34% OPM Calc. on 104,301M KRW) [4]. Yet Pre-Tax swung from +22,445M KRW (2Q26) to -17,851M KRW (3Q26) (a -23,518M KRW / -23.52B KRW non-operating deduction, Calc.; Net loss -12,637M KRW) on quarter-end FX/fair-value marks [4].
- SOOP (`067160.KQ`): 3Q26 revenue 105,687M KRW (+1.8% QoQ, -16.0% YoY); OP 14,522M KRW (+15.0% QoQ, -59.9% YoY) → 13.74% OPM (Calc., vs. 12.16% in 2Q26 and 28.81% in 3Q25) [5].
- Satrec Initiative (`099320.KQ`): 3Q26 revenue 56,188M KRW (+9.9% QoQ, +11.4% YoY); OP surged +502.7% QoQ (+235.6% YoY) from 1,367M to 8,239M KRW → OPM expanded 2.67% (2Q26) → 14.66% (3Q26, Calc.); Net income flipped positive to 3,387M KRW (controlling interest 3,921M KRW, +795.2% QoQ) [6].
- AbClon (`174900.KQ`): Filed an amended R&D agreement with Yuhan Corp (`유한양행`) transferring remaining TIGIT antibody rights for a final 1,000,000,000 KRW (1.00B KRW) settlement while confirming in Item 5(4) zero remaining performance obligations or contingent clawbacks (
추가적인 이행 의무나 우발부채는 존재하지 않습니다) [7].
Takeaway
- Screening Rule: Always pair
OPMwithPre-Tax minus OPon Korean preliminary releases to separate true operating inflections (Satrec +502.7% QoQ OP) from non-operating shocks (HL Mando -92.74B KRW; Suprema -23.52B KRW).
Sources
- DART Kia Corporation (000270.KS) Preliminary Consolidated 3Q26 Earnings Fair Disclosure, 2026.10.30.
- DART Hyundai AutoEver (307950.KS) Preliminary Consolidated 3Q26 Earnings Fair Disclosure, 2026.10.30.
- DART HL Mando (204320.KS) Preliminary Consolidated 3Q26 Earnings Fair Disclosure, 2026.10.30.
- DART Suprema (236200.KQ) Preliminary Consolidated 3Q26 Earnings Fair Disclosure, 2026.10.29.
- DART SOOP (067160.KQ) Preliminary Consolidated 3Q26 Earnings Fair Disclosure, 2026.10.30.
- DART Satrec Initiative (099320.KQ) Preliminary Consolidated 3Q26 Earnings Fair Disclosure, 2026.10.29.
- DART AbClon (174900.KQ) Material Management Report: TIGIT Antibody Joint R&D & Technology Transfer Settlement With Yuhan Corp, 2026.10.30.
Get Primary Korean DART (K-IFRS) & Asia Semiconductor Filing Notes Before Secondary Wires
Receive direct email alerts whenever a new Korean FSS DART preliminary earnings note, treasury-share burn check, or U.S. SEC CapEx cross-check is published. 100% free, one-way analytical record.
Reader Discussion & Filing Notes (0)
Discuss K-IFRS footnotes, DART
rcpNodisclosures, KOSPI/KOSDAQ valuation gaps, or test the falsifiable hypotheses in this note. Free reader accounts take 10 seconds to create.