KRX Names 151 Chronic Low-PBR Firms (0.25x Avg): Conglomerate Audit, KOSDAQ Art. 6(3) Quirk & Book-Shrinkage Accounting
| Issuer & Live Multiples | Valuation Estimate | 6–12M Direction | So What? (Valuation Basis & Catalyst) |
|---|---|---|---|
| Lotte Shopping (023530.KS) Close 81,200 KRW · Consol. PBR 0.13x (Tagged 0.17x) · P/OP 3.35x | UNDERVALUED | ▲ +49–86% Upside | 1H26 OP 342.8B KRW (4.85% OPM); trades at 3.35x annualized OP vs. 604,812 KRW BPS |
| Lotte Chemical (011170.KS) Close 45,900 KRW · Controlling PBR 0.15x (Tagged 0.18x) · ROE 2.46% | UNDERVALUED | ▲ +49–70% Upside | Swung from -943.1B KRW FY25 loss to +183.6B KRW 1H26 OP; BPS 311,664 KRW |
| Taekwang Ind. (003240.KS) Close 823,000 KRW · Float PBR 0.16x (Tagged 0.23x) · Treasury 24.41% | UNDERVALUED | ▲ +55–86% on Burn | 4.28T KRW equity & 24.41% treasury stock lift float-adjusted BPS to 5,090,257 KRW |
| Seohee (035890.KQ) · BGF Eco (126600.KQ) Seohee Post-Burn 0.29x (25% Payout) · BGF Eco 0.37x (BPS +3.3%) | UNDERVALUED | ▲ +58–91% Upside | Operating profit paired with sub-0.40x share cancellation compounds BPS upward |
| SUN&L (002820.KS) · EcoSimplex (038870.KQ) SUN&L 0.06x (Lowest of 151) · EcoSimplex 0.40x (Art. 6(3) Quirk) | FAIR VALUE | ▶ Range-Bound Until OP Turn | 1H26 operating losses (-38.2억 / -15.2억 KRW) keep multiples range-bound until turnaround |
Korea Exchange (KRX) unveiled its first 151 chronic low-PBR companies (96 KOSPI, 55 KOSDAQ; 0.25x average PBR) on November 1, 2026, attaching a visible “Low-PBR” warning tag across retail and institutional trading apps through May 2027 while exempting 34 proactive Value-Up filers for one year.
As of 2026.11.02 · Source: KRX Low-PBR Designation Release (2026.11.01), DART 1H26 Reports & Value-Up Filings, KRX Market Data (2026.10.22 & 2026.10.30) · Derived ratios marked (Calc.).
1. Policy Architecture & Representative Conglomerate Audit (Lotte Shopping, Lotte Chemical, Taekwang Industrial, SUN&L)
- 185 Screened → 34 Grace Period → 151 Tagged: As of the October 22, 2026 cutoff, KRX screened 2,431 listed companies and identified 185 firms that remained in the bottom 25% of their KOSPI sector or bottom 10% of their KOSDAQ sector across all 6 half-years over the past 3 years [1]. After granting a 1-year grace period to 34 firms (18.4%; 24 KOSPI, 10 KOSDAQ) that submitted Value-Up improvement plans, KRX finalized 151 designated firms (6.2% of listed pool: 96 KOSPI, 55 KOSDAQ) with an average PBR of 0.25x and 51 firms (33.8%) below 0.20x [1].
- Conglomerate & HoldCo Concentration: The list includes 40 affiliates across 28 large business groups (averaging 0.24x PBR vs. 0.25x for the other 111 firms) and 10 KFTC-designated holding companies suffering from parent-subsidiary double-counting discounts [1]. Lotte Group placed 3 affiliates—Lotte Himart (0.15x designated; 1H26 equity 9,086.6B KRW [9,086.6억 원], BPS 38,490 KRW, Oct 30 close 5,480 KRW = 0.14x) [10], Lotte Shopping (0.17x), and Lotte Chemical (0.18x)—while Taekwang Group placed 3 affiliates: Daehan Synthetic Fiber (0.19x), Heungkuk Fire (0.20x), and Taekwang Industrial (0.23x) [1].
- Lotte Shopping (023530.KS · Close 81,200 KRW · Consolidated PBR 0.13x · Designated 0.17x): In 1H26 (6M cumulative), Lotte Shopping generated 7,066.6B KRW (7조 666.2억 원) in revenue, 342.79B KRW (3,427.9억 원) in operating profit (OPM 4.85%), and 158.49B KRW (1,584.9억 원) in net income [2]. Against consolidated total equity of 17,109.4B KRW (17조 1,093.9억 원; BPS 604,812 KRW across 28,288,755 issued shares), its October 30 market cap of 2,297.05B KRW (2조 2,970.5억 원) trades at 0.13x total book (0.15x controlling equity of 15조 3,020.5억 원 / BPS 540,924 KRW) and just 3.35x annualized 1H26 operating profit (6,855.8억 원, Calc.) [2][9]. Valuation trajectory: downside support 72,577 KRW (0.12x) → near-term range 81,200–90,722 KRW (0.13–0.15x) → re-rating 120,962–151,203 KRW (0.20–0.25x, +49–86%, Calc.).
- Lotte Chemical (011170.KS · Close 45,900 KRW · Controlling PBR 0.15x · Designated 0.18x): After a FY25 operating loss of -943.12B KRW (-9,431.2억 원), Lotte Chemical swung to a 1H26 operating profit of 183.62B KRW (1,836.2억 원, OPM 1.72%) and net profit of 227.95B KRW (2,279.5억 원) on sales of 10조 6,768.9억 원 [3]. Controlling equity stands at 13,331.5B KRW (13조 3,315.4억 원; BPS 311,664 KRW), but 6M annualized net profit (4,559.0억 원) yields only a 2.46% ROE on total equity (18조 5,430.5억 원, Calc.) [3]. Trajectory: support 40,516 KRW (0.13x) → range 45,900–56,100 KRW (0.15–0.18x) → recovery 68,566–77,916 KRW (0.22–0.25x, +49–70%, Calc.).
- Taekwang Industrial (003240.KS · Close 823,000 KRW · Float-Adjusted PBR 0.16x · Designated 0.23x) & SUN&L (002820.KS · Close 1,040 KRW · 0.06x Lowest): Taekwang holds 4,284.1B KRW (4조 2,841.2억 원) in equity with a 13.4% debt-to-equity ratio and 24.41% treasury stock (271,769 of 1,113,400 shares), lifting float-adjusted BPS across 841,631 shares to 5,090,257 KRW vs. 3,847,780 KRW on issued shares (1H26 operating loss -124.8억 원; trajectory 769,556 KRW → 823,000–961,945 KRW → 1,272,564–1,527,077 KRW [+55–86%] upon treasury cancellation) [4]. Wood-panel maker SUN&L ranked lowest among all 151 companies at 0.06x PBR (equity 2,271.4억 원, BPS 18,016 KRW, market cap 131.1억 원), remaining range-bound between 901 KRW (0.05x) and 1,040–1,261 KRW until its 1H26 operating loss (-38.2억 원) turns positive toward 1,802–2,162 KRW (0.10–0.12x, +73–108%) [5].
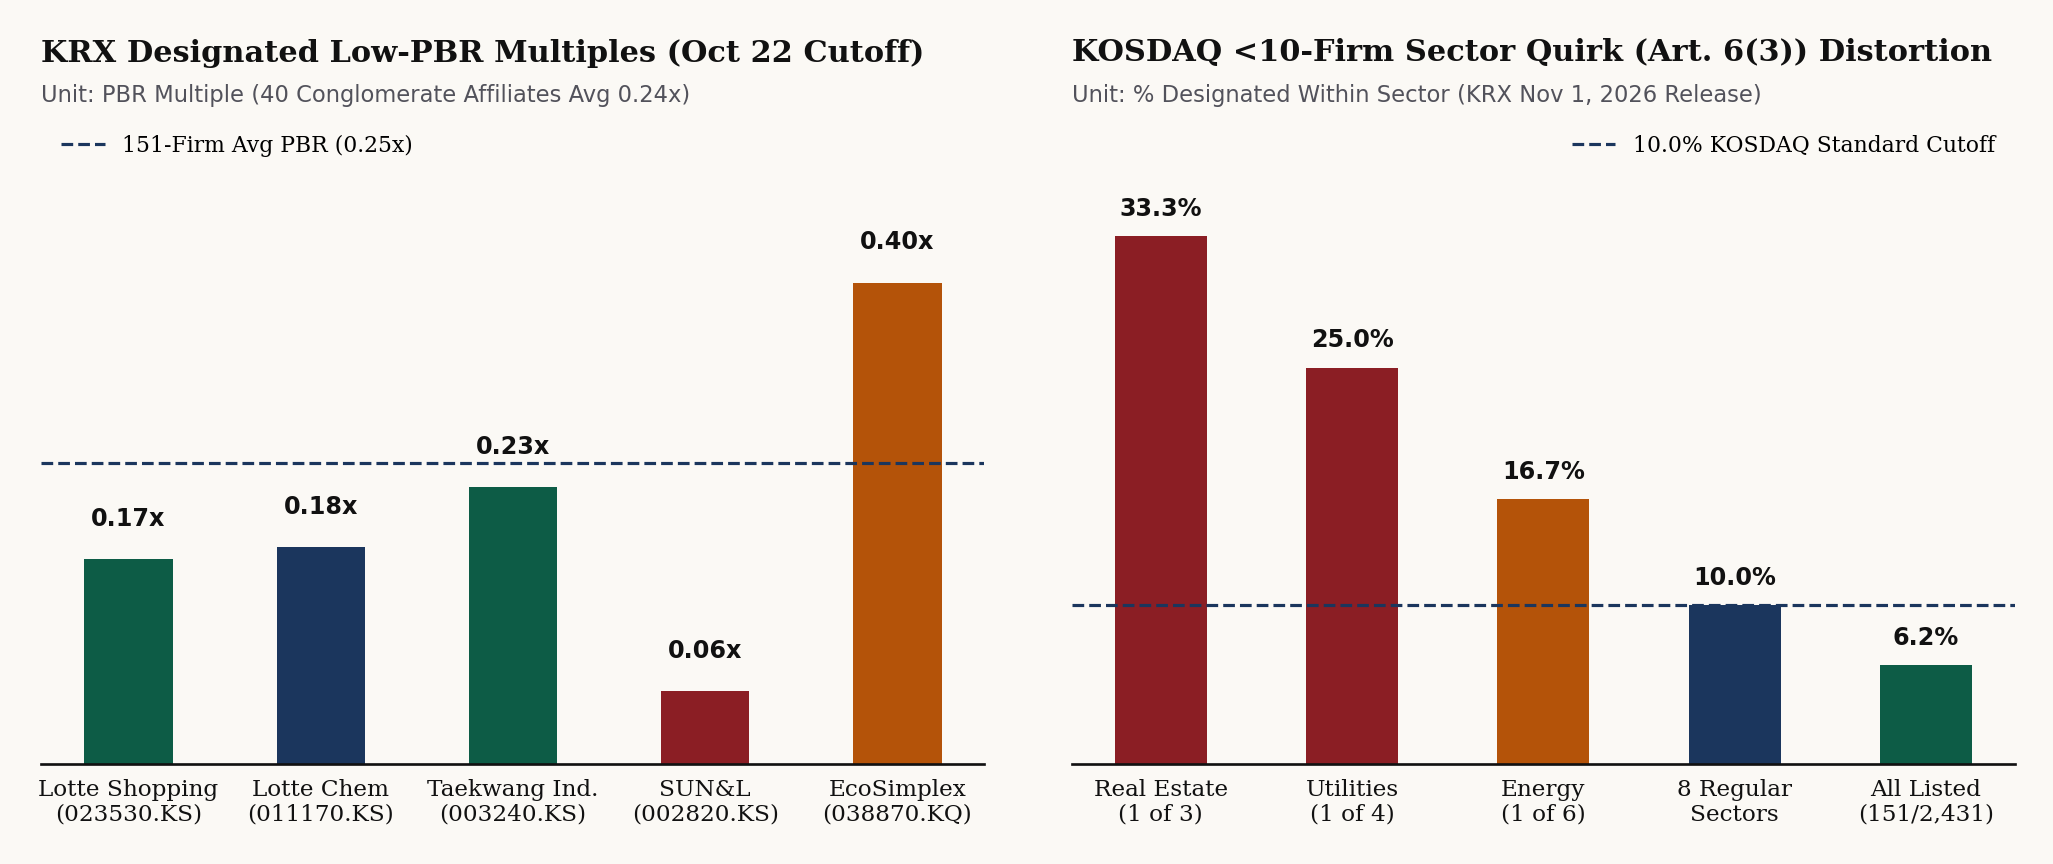
Left: KRX designated low-PBR multiples as of the October 22, 2026 cutoff vs. the 151-firm average (0.25x). Right: KOSDAQ Article 6(3) small-sector designation rate distortion (Real Estate 33.3%, Utilities 25.0%, Energy 16.7%) vs. the 10.0% standard rule.
2. Policy Merits vs. Two Structural Flaws: Nudge Effect, KOSDAQ Art. 6(3) Quirk & Book-Shrinkage Accounting
- What Worked (Behavioral Nudge Across 34 Grace-Period Filers — Seohee Construction 035890.KQ): Attaching a visible MTS warning tag prompted 34 of 185 candidates (18.4%) to file formal Value-Up plans before the deadline [1]. Seohee Construction (Oct 30 close 1,906 KRW, 1H26 equity 1조 2,384.3억 원, 1H26 OP 468.9억 원) pledged to cancel all 22.22M remaining treasury shares (22,219,921 shares) by February 2027 and raise its dividend payout ratio to 25%, lifting post-burn effective BPS to 6,681 KRW (0.29x PBR; trajectory 1,670 KRW → 1,906–2,338 KRW → 3,006–3,340 KRW [0.45–0.50x, +58–75%]) [7][11].
- Structural Flaw 1 — KOSDAQ <10-Firm Sector Quirk (Article 6(3), EcoSimplex 038870.KQ): Under Article 6(3) of the KRX Low-PBR Selection Guidelines, any KOSDAQ sector with fewer than 10 listed companies automatically designates its single lowest-PBR firm below 0.50x and sector mean [1]. While the 8 regular KOSDAQ sectors (10+ firms) applied bottom-10% cutoffs (Materials 0.28x, Industrials 0.31x, IT 0.39x, Healthcare 0.51x), the 3 small sectors suffered outsized designation rates: Real Estate 33.3% (1 of 3), Utilities 25.0% (1 of 4), and Energy 16.7% (1 of 6) [1]. EcoSimplex (Oct 30 close 1,940 KRW, 1H26 equity 754.2억 원, BPS 5,381 KRW, 1H26 OP -15.2억 원) was tagged at 0.40x PBR on October 22 (0.36x on Oct 30) solely because KOSDAQ Utilities has only 4 listed firms (trajectory 1,614 KRW → 1,940–2,152 KRW → 2,421–2,691 KRW, +25–39%) [6].
- Structural Flaw 2 — The Denominator-Shrinkage Accounting Trap vs. Accretive Low-PBR Buybacks (BGF Eco Materials 126600.KQ): In the Gordon-implied identity $P/B = (ROE - g)/(k_e - g)$, shrinking book equity $B$ via one-off cash dividends in a loss-making firm drains cash and reduces market cap $P$ dollar-for-dollar, leaving the multiple trapped below 0.30x. Conversely, when an operating-profitable issuer like BGF Eco Materials (Oct 30 close 3,040 KRW, 1H26 OP 44.3B KRW [44.3억 원], pre-burn equity 5,045.0억 원, BPS 8,038 KRW) repurchases and cancels 6.00% of issued shares (3,764,752 shares [376.5만 주] at a 3,850 KRW tender price = 144.9억 원) at 0.37x–0.38x PBR, remaining shareholders' effective BPS compounds upward by +3.3% to 8,305 KRW (trajectory 3,040 KRW → tender 3,850 KRW [+26.6%] → re-rating 4,983–5,813 KRW [0.60–0.70x, +64–91%]) [8].
| Issuer & Policy Cohort | 1H26 DART Equity, BPS & Operating Profit | 3-Stage Valuation Trajectory (Oct 30 Close) |
|---|---|---|
| Lotte Shopping (023530.KS) Designated 0.17x · Total PBR 0.13x |
Equity 17조 1,093.9억 원 (BPS 604,812 KRW); 1H26 OP 3,427.9억 원 (OPM 4.85%, P/OP 3.35x) | Close 81,200 KRW: 72,577 → 81,200–90,722 → 120,962–151,203 KRW (+49–86%) |
| Lotte Chemical (011170.KS) Designated 0.18x · Controlling 0.15x |
Controlling Equity 13조 3,315.4억 원 (BPS 311,664 KRW); 1H26 OP +1,836.2억 원 (ROE 2.46%) | Close 45,900 KRW: 40,516 → 45,900–56,100 → 68,566–77,916 KRW (+49–70%) |
| Taekwang Ind. (003240.KS) Designated 0.23x · Float PBR 0.16x |
Equity 4조 2,841.2억 원; Treasury 24.41% (271,769 sh); Float BPS 5,090,257 KRW | Close 823,000 KRW: 769,556 → 823,000–961,945 → 1,272,564–1,527,077 KRW (+55–86%) |
| SUN&L (002820.KS) & EcoSimplex (038870.KQ) | SUN&L 0.06x (BPS 18,016 KRW, OP -38.2억 원); EcoSimplex 0.40x (Utilities 1 of 4, BPS 5,381 KRW) | SUN&L 1,040 KRW (range 1,040–1,261); EcoSimplex 1,940 KRW → 2,421–2,691 KRW (+25–39%) |
| Seohee Const. (035890.KQ) & BGF Eco (126600.KQ) | Seohee: 22.22M sh full cancel + 25% payout (BPS 6,681 KRW); BGF Eco: 6.00% burn lifts BPS 8,038→8,305 KRW (+3.3%) | Seohee 1,906 → 3,006–3,340 KRW (+58–75%); BGF Eco 3,040 → 4,983–5,813 KRW (+64–91%) |
Key Takeaways for Institutional Allocators
- Separate Operating Cash Generators from Chronic Operating Losers: Within the 151 tagged names, companies generating positive operating profit or holding massive treasury blocks—such as Lotte Shopping (3.35x annualized P/OP, 0.13x consolidated book) and Taekwang Industrial (24.41% treasury shares, 0.16x float-adjusted book)—offer asymmetric re-rating potential (+49–86%) once capital allocation shifts toward share cancellation.
- Exploit Sector-Cutoff Anomalies & Accretive Buybacks: KOSDAQ Article 6(3) mechanically penalized small-sector constituents like EcoSimplex at 0.40x while sparing crowded-sector peers at 0.29x–0.38x. True per-share compounding requires pairing sub-0.40x share cancellations with positive operating earnings, as demonstrated by Seohee Construction (0.29x post-burn) and BGF Eco Materials (BPS +3.3% from a 6.00% tender cancellation).
Primary Sources & DART Filings
- Korea Exchange (KRX) & Chosun Ilbo: First Disclosure of 151 Chronic Low-PBR Firms & Selection Guidelines (Article 6(3)), 2026.11.01.
- DART Lotte Shopping (023530) 1H26 Semi-Annual Report (K-IFRS Consolidated), 2026.08.14.
- DART Lotte Chemical (011170) 1H26 Semi-Annual Report (K-IFRS Consolidated), 2026.08.14.
- DART Taekwang Industrial (003240) 1H26 Semi-Annual Report (K-IFRS Consolidated), 2026.08.14.
- DART SUN&L (002820) 1H26 Semi-Annual Report (K-IFRS Consolidated), 2026.08.14.
- DART EcoSimplex (038870) Amended 1H26 Semi-Annual Report, 2026.10.06.
- DART Seohee Construction (035890) Corporate Value-Up Plan Disclosure, 2026.10.30.
- DART BGF Eco Materials (126600) Decision on Treasury Share Cancellation (6.00%), 2026.10.30.
- KRX Information Data System: Daily Closing Prices & Market Capitalization, 2026.10.22 & 2026.10.30.
- DART Lotte Himart (071840) 1H26 Semi-Annual Report, 2026.08.14.
- DART Seohee Construction (035890) Corporate Value-Up Voluntary Disclosure, 2026.11.02.
Get Primary Korean DART (K-IFRS) & Asia Semiconductor Filing Notes Before Secondary Wires
Receive direct email alerts whenever a new Korean FSS DART preliminary earnings note, treasury-share burn check, or U.S. SEC CapEx cross-check is published. 100% free, one-way analytical record.
Reader Discussion & Filing Notes (0)
Discuss K-IFRS footnotes, DART
rcpNodisclosures, KOSPI/KOSDAQ valuation gaps, or test the falsifiable hypotheses in this note. Free reader accounts take 10 seconds to create.