Tesla 3Q26 Form 10-Q Audit: Stripping Note 11 Tariff Refunds (~16.8% Auto, ~23.8% Energy) & +69.4% R&D Surge
| Issuer & Live Multiples | Valuation Estimate | 6–12M Direction | So What? (Valuation Basis & Catalyst) |
|---|---|---|---|
| Tesla (TSLA) $399.81 · Mkt Cap $1.58T · P/E 370.14x · P/B 18.18x | OVERVALUED | ▼ Cautious | Ex-tariff refund Auto GM (16.8%) and Energy GM (23.8%) leave 370.1x P/E vulnerable to 4Q reset |
Backing out Form 10-Q Note 11 IEEPA tariff refunds lowers Tesla's 3Q26 ex-credit Auto GPM from 18.1% to ~16.8% and Energy GPM from 33.1% to ~23.8%, while R&D (+69.4% YoY) drove GAAP OPM to 2.6%.
As of 2026.10.28 · Source: Tesla 3Q26 Form 8-K Exhibit 99.1 & Form 10-Q · Derived ratios marked (Calc.).
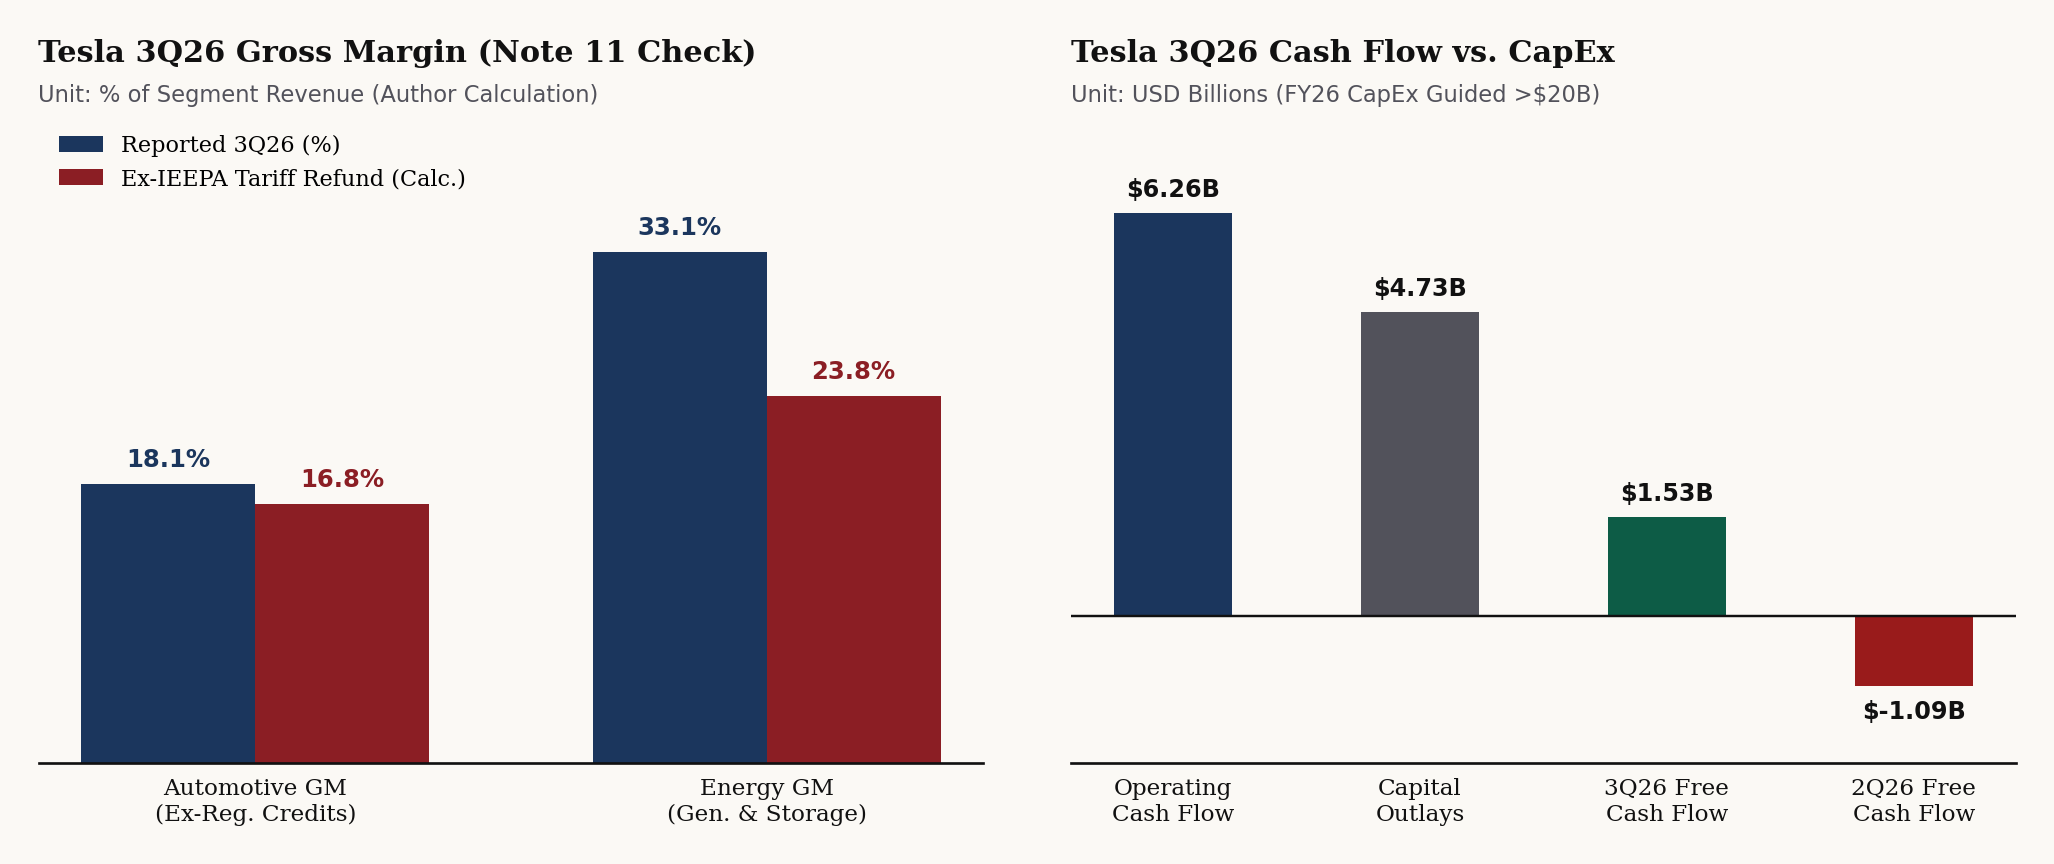
Left: Reported 3Q26 segment gross margins vs. simple arithmetic reversal of Note 11 IEEPA tariff refunds (Calc.). Right: 3Q26 bridge from GAAP operating income to operating cash flow and free cash flow. Source: Tesla Form 8-K & Form 10-Q [1][2].
1. Note 11 IEEPA Tariff Refund Strip: 18.1% → ~16.8% Auto, 33.1% → ~23.8% Energy
- Reported Headline vs. Note 11 Entries: 3Q26 Gross Profit rose +8.7% YoY (+15.6% QoQ) to $5.494B (+$440M YoY), with reported ex-credit Auto GPM at 18.1% (vs. 16.3% in 2Q26, 15.4% in 3Q25; reg credits = $113M) and Energy GPM at 33.1% [1][2]. However, following the Feb 2026 U.S. Supreme Court IEEPA ruling, Note 11 discloses one-time tariff refunds reducing Auto COGS by $260M and Energy COGS by $526M, alongside a $339M customer refund deducted from Energy revenue [2].
- Normalized Segment Margins (Arithmetic Reversal, Calc.):
•Auto Ex-Credit GPM (adding back $260M COGS refund): 18.1% → ~16.8%[1][2].
•Energy GPM (adding back $526M COGS refund + $339M revenue rebate): 33.1% → ~23.8%[2]. - FSD & Services: FSD Supervised active users hit 1.74M (+67.3% YoY, ex-free trials, booked in Auto); Services & Other GP reached $734M [1][2].
| Item | 3Q26 Figures |
|---|---|
| Total Revenue | $28.046B, -0.2% YoY (deliveries -2.1%, Services & Other revenue +32.5%, growth rates Calc.) |
| Total Gross Margin | 19.6%, gross profit $5.494B (+160bp YoY, vs. 16.8% in 2Q26) |
| Automotive Margin (Ex-Credits) | Reported 18.1%; ~16.8% after reversing $260M tariff refund in COGS (Calc.) |
| Energy Margin | Reported 33.1%; ~23.8% after reversing $526M COGS refund and $339M customer refund (Calc.) |
| Operating Expenses | $4.776B (+39.2% YoY, Calc.) / R&D $2.761B, SG&A $2.015B |
| Operating Income (GAAP) | $718M, -55.8% YoY (Calc.) / Operating margin 2.6% (vs. 5.8% in 3Q25 and 1.4% in 2Q26) |
| Operating Cash Flow & CapEx | OCF $6.263B (+33.3% QoQ, Calc.) / CapEx $4.732B (1Q–3Q cumulative $13.01B) |
| Free Cash Flow & Ending Cash | +$1.531B (vs. -$1.092B in 2Q26, -61.6% YoY, Calc.) / Cash & ST investments $45.45B |
2. OpEx Surge (+39.2% YoY) vs. GAAP OPM (2.6%)
- AI & Robotics R&D Front-Loading: 3Q26 OpEx rose +$1.346B (+39.2% YoY) from $3.430B to $4.776B: R&D surged +69.4% YoY ($1.630B → $2.761B), SG&A rose +29.0% YoY to $2.015B, and SBC climbed from $663M to $1.165B (CEO performance award recognition) [2].
- Operating Income Impact: GAAP OP was $718M (2.6% OPM) — up from 1.4% in 2Q26, but -322bp YoY vs. 5.8% ($1.624B) in 3Q25 [1][2].
3. CapEx ($13.01B 9M26), FCF Rebound (+$1.531B) & $30B Standby Line
- Cortex Compute CapEx & 4Q26 Hurdle: 3Q26 CapEx jumped +110.5% YoY to $4.732B (vs. $2.248B in 3Q25); 9M26 CapEx hit $13.01B (>2x 9M25's $6.13B) as Giga Texas Cortex 1 (>105MW) and Cortex 2 (>120MW) scaled toward a 400MW year-end target [1][2]. Guiding FY26 CapEx >$20B implies
4Q26 CapEx > $6.99B[2]. - Cash Flow & Liquidity Buffer: 3Q26 OCF rose +$1.566B QoQ ($4.697B → $6.263B; TTM OCF $18.71B) while CapEx stepped down -$1.057B QoQ from 2Q26's $5.789B, swinging FCF from -$1.092B (2Q26) to +$1.531B (3Q26, -61.6% YoY) [1]. Ending cash/investments rose +$1.92B QoQ to $45.45B, backed by a new $30B undrawn credit facility (entered Sept 2026) [2].
Takeaway & Next-Quarter Checks
- 4Q26 Checks: (1) Do Auto (~16.8% baseline) and Energy (~23.8% baseline) hold margins without Note 11 tariff refunds? (2) Does 4Q26 CapEx clear the >$6.99B hurdle while keeping FCF positive?
Sources
- Tesla Q3 2026 Update (Form 8-K Exhibit 99.1), 2026.10.21.
- Tesla Q3 2026 Form 10-Q (SEC EDGAR), 2026.10.22.
Get Primary Korean DART (K-IFRS) & Asia Semiconductor Filing Notes Before Secondary Wires
Receive direct email alerts whenever a new Korean FSS DART preliminary earnings note, treasury-share burn check, or U.S. SEC CapEx cross-check is published. 100% free, one-way analytical record.
Reader Discussion & Filing Notes (0)
Discuss K-IFRS footnotes, DART
rcpNodisclosures, KOSPI/KOSDAQ valuation gaps, or test the falsifiable hypotheses in this note. Free reader accounts take 10 seconds to create.